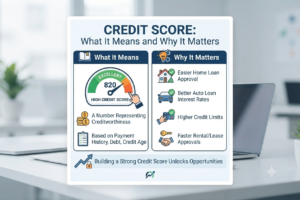
A credit score is a numerical representation based on information in a person’s credit history. Financial institutions may use credit reports and credit scores as one factor when assessing applications for loans, credit cards or other financial products.
Payment history is an important part of many credit assessment systems. Regularly making loan and credit-card payments on time can help maintain a consistent credit record. Missed or delayed payments may be recorded and can affect future credit applications depending on the applicable reporting system.
Credit utilisation can also be relevant for some scoring models. It generally refers to how much of an available revolving credit limit is being used. The effect varies according to the scoring model and the individual’s overall credit profile.
Consumers should periodically review their credit report. Checking the report can help identify inaccurate personal information, incorrectly reported payments or unfamiliar accounts. If an error is discovered, the consumer can follow the dispute process provided by the relevant credit bureau or lender.
Applying for several credit products within a short period may also have an effect depending on the lender and scoring system. It can therefore be useful to compare suitable options before submitting multiple applications.
A credit score is not the only factor lenders consider. Income, employment, existing debt, repayment capacity, loan purpose and the lender’s own eligibility requirements can also play a role.
There is no single action that can instantly create a strong credit history. Good credit management generally comes from consistent financial habits over time.
Paying obligations on time, keeping borrowing manageable, reviewing credit reports and correcting inaccurate information can all contribute to responsible credit management.
Understanding how credit works can help consumers become more aware of their financial profile and prepare better before applying for loans or other forms of credit.